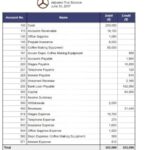
But here’s a basic run-through of what is included in a simple trial balance. Once you complete the process, you can close your trial balance. Save the document itself, which can be helpful if you need to perform the process again for a longer period.
- You can use this trial balance as a starting point to analyze your accounts before adjusting your journal entries.
- While modern accounting software can minimize data entry errors and similar mistakes, trial balances still have their uses among internal company leadership.
- If it divides exactly, you may have made a transposition error (e.g., entering 1985 rather than 1895).
- Enrol and complete the course for a free statement of participation or digital badge if available.
- While there are no formal requirements for a trial balance, it typically consists of at least three columns.
- Make sure that the accounts listed on your trial balance are the same as on your general ledger.
- With accounting software, business owners don’t have to wait for the end of the year to make a trial balance and assess their financial information.
It also serves as a review stage to point out discrepancies and rectify them. It’s usually the first stage of preparing official financial records and statements. When the trial balance does not balance, try re-totaling the two columns.
What is the formula for trial balance?
For instance, if a transaction involving payment of a $ 100 account payable is never recorded, the trial balance totals still balance, but at an amount that is $ 100 too high. A trial balance is a statement prepared to ensure that the transactions for a period have been duly recorded in the journal and properly posted to the relevant ledger accounts. https://kelleysbookkeeping.com/how-to-calculate-improve-amazon-days-sales-in/ A trial balance is an internal report that includes all of the account balances in your general ledger. It can also serve as a test to ensure accuracy before an audit. Trail balance is worksheet which consists of all ledger balances and columned them as debit and credit. It is prepared at end of reporting period and repeated for every period.
How to Prepare an Adjusted Trial Balance for Your Business – The Motley Fool
How to Prepare an Adjusted Trial Balance for Your Business.
Posted: Wed, 18 May 2022 07:00:00 GMT [source]
All three of these types have exactly the same format but slightly different uses. The unadjusted trial balance is prepared on the fly, before adjusting journal entries are completed. It is a record of day-to-day transactions and can be used to balance a ledger by adjusting entries. You’ll record your credit balances in the center column (the credit column), while your debit balances are recorded in the far right column (the debit column). The total credit balance will appear at the bottom of the columns. If the debit and credit columns of the trial balance do not agree, this indicates the presence of one or more errors in the journal or ledger.
Total Amount Method:
It’s worth noting that a trial balance differs from a balance sheet, as the latter is something that is distributed outside of the accounting team, and sometimes the business. The trial balance is now ready for use in the preparation of financial statements. While we still have not prepared financial statements, we have captured the activity and organized it into a trial balance. Next up is editing the information before we can publish our story in financial statements. Preparing a trial balance regularly helps a business in spotting errors in its books. With accounting software, business owners don’t have to wait for the end of the year to make a trial balance and assess their financial information.
This can be assessed using the balances of both the debit and credit side of the trial balance. Because if the total on both sides agrees or equates, then it means that ledger postings are posted in an accurate manner. It also confirms the rules of the double entry system that all the entries have a double effect. A trial balance may agree and yet there may be one or more errors in the books of accounts. For example, if a journal entry has been omitted, the debit and credit columns of the trial balance will still agree. The basic purpose of preparing a trial balance is to test the arithmetical accuracy of the ledger.
Record credit and debit balances on your trial balance
If you check the above trial balance again, you’ll realize that this list of balances is also a summary of all transactions made during the accounting period. There are no complexities regarding double entries here; at this stage, it has been completed. Debit balances are merely listed on the debit of the trial balance, with credit balances on the credit. The trial balance is not an account; it is simply a list of all the debit and credit balances.
Limitations aside, a trial balance can still be a valuable tool for evaluating your company’s finances, and it can be helpful when you examine your company’s financial statements. A trial balance is called a trial balance because there will always be equal amounts entered on the debit and credit sides of the ledger. At the bottom of the debit and credit column, calculate the total sum of all entries. The main purpose of a trial balance is to ensure that bookkeeping entries are correct. But it’s also worth extending your knowledge to how it paints an overall picture of your business’s accounts. A company’s transactions are recorded in a general ledger and later summed to be included in a trial balance.
It is prepared on a particular date to summarize the records and check the arithmetical accuracy of the books of accounts. The trial balance is a source of locating errors in a company’s ledger. Companies can use a trial balance to keep track of their financial position, and so they may prepare several different types of trial balance throughout the financial year.
- This is because if the debit and credit side of the trial balance agrees, then it is assumed that the journal, subsidiary books, and ledgers are correctly and properly maintained.
- The general purpose of producing a trial balance is to ensure that the entries in a company’s bookkeeping system are mathematically correct.
- For instance, if a transaction involving payment of a $ 100 account payable is never recorded, the trial balance totals still balance, but at an amount that is $ 100 too high.
- When you prepare your trial balance, include as much detail as possible, such as the date of the accounting period.
- So, you can’t rely on a trial balance to reveal every issue in your business accounts.
It is also important to note that even when the trial balance is considered balanced, it does not mean there are no accounting errors. For example, the accountant may have failed to record an account or classified a transaction incorrectly. These are accounting errors that would not show up in the trial balance. This check might reveal a basic manual data entry mistake or entries made in the wrong column or account.
How Are Accounts Listed in Trial Balance?
The trial balance summarizes all accounts and balances the totals in the debit and credit columns. The financial information, which is classified and grouped in the various ledger accounts, is now totaled for each account. Also, the Preparing A Trial Balance debit and credit balances are listed on the trial balance, including the final balance of the cash account. A trial balance can be used to detect any mathematical errors that have occurred in a double entry accounting system.